A credit report can influence your ability to qualify for a mortgage, finance a car, rent an apartment, or obtain certain types of credit. Yet many people pay closer attention to their credit score than to the information behind it. Reading your reports periodically can help you see what lenders may see, catch reporting mistakes, and recognize potential identity theft.
Start With Your Personal Information
A credit report typically contains identifying information such as your name, previous addresses, and variations of your name reported by creditors. This section does not determine your creditworthiness, but inaccuracies deserve attention. An unfamiliar address or name variation may be a simple reporting error. It can also be a reason to examine the rest of the report more closely.
Read Each Account as a History
The account section, sometimes called the tradeline section, provides much of the useful detail. Credit cards, mortgages, auto loans, student loans, and other reported accounts may appear here. Look for late payments you believe were made on time, incorrect balances, closed accounts listed as open, or accounts that do not belong to you.
Know What Inquiries Mean
Credit reports may show inquiries from organizations that accessed your credit information. Hard inquiries typically occur after you apply for credit and can affect credit scores. Soft inquiries, such as certain account reviews or checks of your own credit, generally do not affect your credit score.
A hard inquiry you cannot explain may indicate that someone applied for credit using your information. Contacting the company associated with the inquiry can help determine what happened.
Dispute Information That Is Wrong
Consumers have rights under federal credit reporting law to dispute inaccurate or incomplete information. A dispute should clearly identify the account and error, explain what should be corrected, and include supporting records when available.
Keep copies of correspondence, account statements, payment confirmations, and dispute results. Documentation becomes especially important when incorrect information remains after repeated attempts to fix it.
More serious situations may require additional help. An attorney for false credit reporting may be relevant when inaccurate information continues to cause harm despite appropriate disputes, depending on the circumstances.
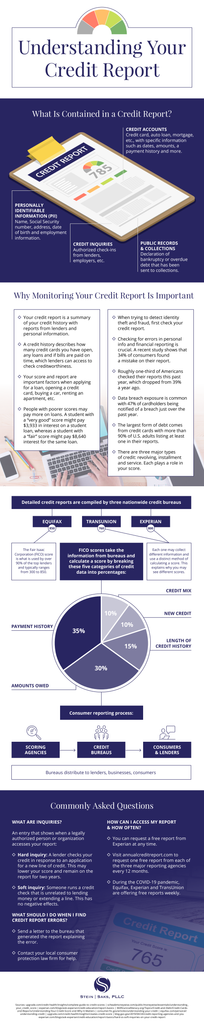
Your credit report is more useful when treated as a financial record rather than simply a pathway to a score. A periodic review also gives you time to correct legitimate problems instead of discovering them while trying to finance a home, car, or other major purchase. Check out the infographic below for more information.